ServicesMergers and Acquisitions
Mergers and Acquisitions in Lockhart, TX
When two private companies combine, or one buys another, the deal turns on details: structure, working capital and the terms that carry past closing. We run small and mid-sized M&A deals with the same few people from the first call to funding, so nothing gets lost in a handoff.
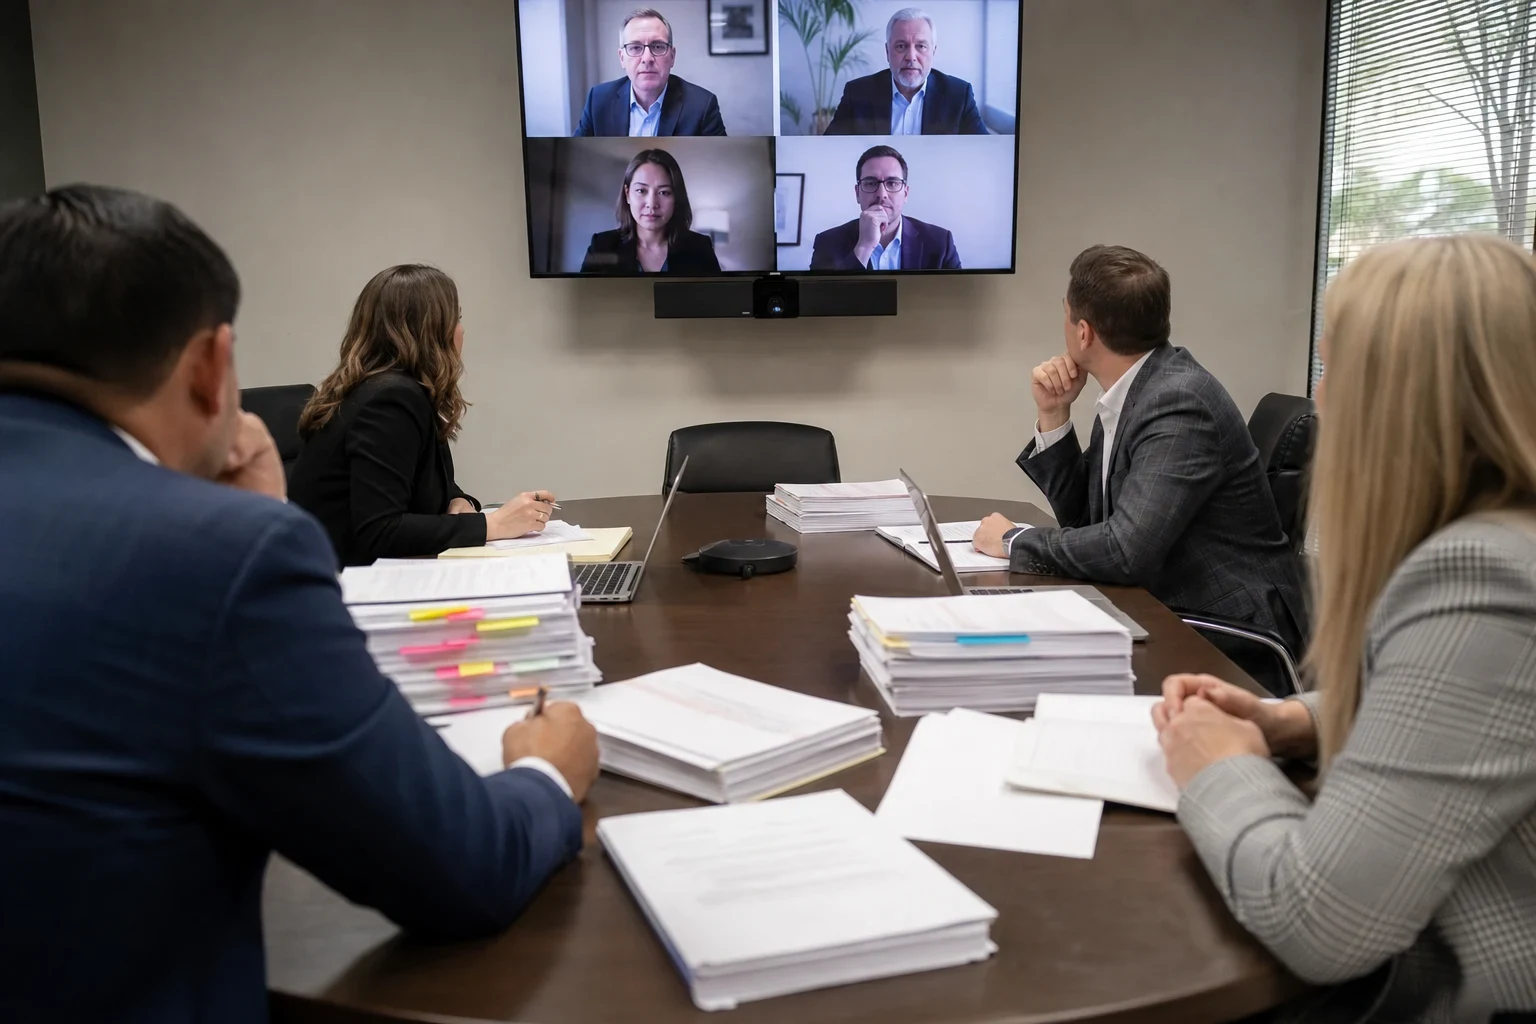
What M&A work looks like for a private company
Most mergers and acquisitions we handle are not headline deals. They are a competitor buying the shop down the road, two owners combining operations to share overhead, or a growing company adding a second location or product line. The mechanics match a larger deal, with less room for error. A buyer's financing depends on verified earnings, and a seller's after-tax result depends on whether the deal is an asset purchase or a stock purchase.
We represent one side of the deal and keep a small crew on it. The person who reads your financials in the first week is the same person on the due diligence calls months later. That continuity matters because M&A deals stall over facts someone forgot: a lease assignment clause, a customer contract that needs consent to transfer, an add-back the buyer's lender will not accept.
If you are selling outright with no combination involved, our Sell a Business page covers that path. This page is for deals where companies combine, or where an operating business is buying another.
What our M&A work includes
Valuation and deal modeling
We start with a free, confidential valuation built on adjusted earnings, with owner compensation normalized and one-time expenses pulled out. For a merger, we model both companies and the combined entity so each owner sees what they contribute and what they end up holding.
Target search or buyer outreach
On the buy side, we identify companies that fit your criteria and approach their owners quietly. On the sell side, we market to strategic acquirers under signed nondisclosure agreements, and new listings go to registered buyers first.
Letter of intent and structure
We negotiate the letter of intent: price, asset versus stock purchase, cash at close, seller note, earnout, working capital target and the length of exclusivity. Most of the money in a deal is decided here, before the lawyers draft the purchase agreement.
Due diligence coordination
We organize the data room and track requests for tax returns, bank statements, payroll records, contracts and leases. When a question comes up, we answer it or route it to the right person so diligence does not drag.
Working with your attorney and CPA
We are not your lawyer or tax advisor. We work alongside them and give them the terms and documents they need, so the purchase agreement and the tax treatment match what was negotiated.
Closing and transition terms
We keep the closing checklist moving through lender approval, landlord consent and final adjustments. We also help set realistic terms for the seller's time in the business after closing.
Signs an M&A deal is the right move
A competitor has made an offer
An unsolicited offer is a starting point, not a valuation. Before you answer, it helps to know what your business would bring with more than one buyer at the table.
You have outgrown your capacity
When growth is capped by staff, equipment or territory, buying an existing company can be faster than building. You get customers, employees and systems that are already working.
Two owners keep talking about combining
Shared overhead and better purchasing power make sense on paper. The hard part is setting relative value and deciding who runs what, which is where an outside party earns its keep.
Your best buyer is strategic
Some businesses are worth more to a company in the same industry than to an individual buyer, because the acquirer can cut duplicate costs. That gap can show up in the price.
You want out, but not all at once
A partial sale with an earnout or rollover equity lets you take money off the table and stay involved for a set period.
How we run an M&A deal
- 1
Confidential first conversation
By phone, video or at our office, we learn what you own or want to buy, your timeline and what a good outcome looks like to you. Nothing about your company leaves that conversation.
- 2
Valuation and strategy
We normalize the financials, set a value range and choose the approach: targeted outreach to a short list of acquirers, or a wider confidential search.
- 3
Outreach and offers
Interested parties sign an NDA before they see a company name or financials. We collect indications of interest, compare them on terms rather than headline price alone, and negotiate the letter of intent.
- 4
Due diligence
Usually the longest stretch. The buyer's team and lender verify revenue, expenses, contracts and liabilities, and we keep the request list current so both sides know what is outstanding.
- 5
Purchase agreement and closing
Attorneys draft the definitive agreement covering reps and warranties, indemnification, the non-compete and the working capital adjustment. We coordinate signatures, funding and the handoff.
What affects the cost of an M&A deal
Our fee depends on the size and complexity of the deal, and we walk through how it is calculated on the first call. Listing with us costs nothing at the start. There is no retainer to sign and no fee tucked into the fine print. Our rule is simple: We Only Get Paid When The Seller Does.
- Size of the deal
- Larger transactions involve more parties, more documents and usually a longer diligence period.
- Condition of the books
- Clean accrual-based financials that tie to tax returns move faster. When records mix personal expenses or run on a cash basis, more work goes into normalizing them before a buyer or lender will rely on the numbers.
- Deal structure
- A straight asset purchase is simpler than a stock purchase with an earnout, seller financing or rollover equity. Each added piece means more negotiation and more drafting.
- Third-party consents
- Leases, franchise agreements, permits and key customer contracts may need approval to transfer. Each consent adds time, and sometimes a fee from the other party.
- Outside advisors
- Your attorney, CPA and any quality of earnings review bill separately. We help you scope that work so you pay for what the deal actually needs.
M&A questions we hear from owners
Something not covered here? (512) 621-7659
What is the difference between a merger and an acquisition for a small company?
In an acquisition, one company buys another's assets or stock, and the seller usually exits or stays on for a transition. In a merger, two companies combine and the owners share the new entity in proportion to what each brings. Among private businesses, acquisitions are far more common, and many deals called mergers are acquisitions where the seller keeps a minority stake.
Should I sell assets or stock?
Buyers usually prefer asset purchases because they get a stepped-up tax basis and leave unknown liabilities behind. Sellers often prefer stock sales for tax reasons and simplicity. The right answer depends on your entity type and tax position, so we lay out the tradeoffs and have your CPA run the numbers before the letter of intent is signed.
Will my staff or customers find out I am talking to acquirers?
Not from us. Your company first goes out as a blind profile with no name or identifying details. A prospective buyer signs a nondisclosure agreement before learning who you are, and site visits happen after hours or are framed so they do not raise questions. We decide together when key employees are told, usually late in diligence.
What is a working capital peg?
It is the agreed level of receivables, inventory and payables that should be in the business at closing. If actual working capital lands above or below that target, the price adjusts. It is one of the most disputed terms in small M&A, so we set it early from a trailing average instead of leaving it to the last week.
Do you work with companies outside Lockhart?
Yes. We work with owners and acquirers in Lockhart, Luling, San Marcos, Kyle, Buda and the surrounding area, and meetings can happen at our office or by phone and video. Strategic buyers can come from anywhere, so we do not limit outreach to one town.
How long does an acquisition take?
It depends on how prepared the financials are, how the buyer is financing the deal and how many consents are needed. Lender underwriting and landlord approvals are the usual sources of delay. After we review your numbers, we give you a realistic timeline instead of a hopeful one.
Talk through your deal before you sign anything
Bring the offer, the idea or just the question. We will tell you what your company is worth, how the deal could be structured and what to watch for, at no cost and in confidence.